All Categories
Featured
Understanding 2026 Medicare Benefit Rules and Seniors
Optimizing Indexed Universal Life Policy Benefits for Ret...
Selecting Your Best 2026 Medicare Supplement Coverage
Selecting Your Best 2026 Medicare Supplement Coverage
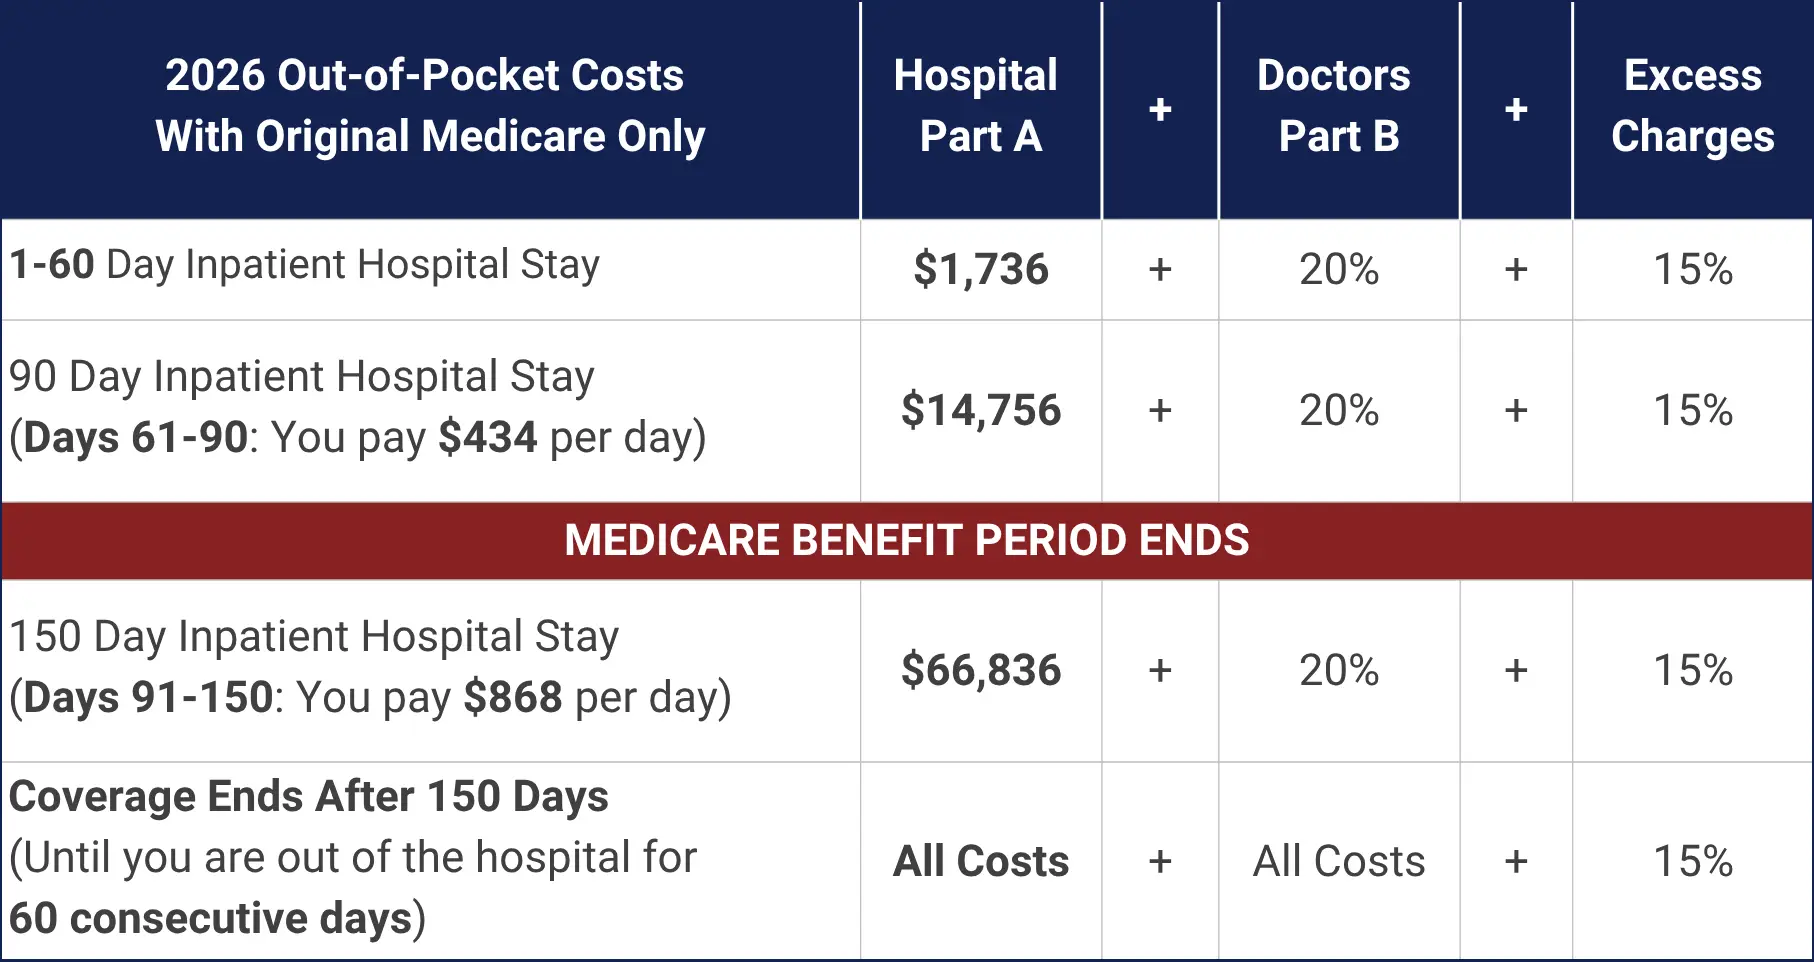
As you compare Medicare Supplement insurance strategies, consider just how much healthcare you require, how often you go to the physician and how much you can afford to pay towards your medical expenses yourself. Each Medigap plan has a different level of protection, so you should find one that fits your specific needs.
Medigap plans pay for some or all of your remaining expenses, depending on your strategy letter. Leading plans Part A coinsurance Yes Yes Yes Part B coinsurance Yes Yes Yes Blood transfer (3 pints) Yes Yes Yes Part A hospice care Yes Yes Yes Competent nursing facility Yes Yes Yes Part A deductible Yes Yes Yes Part B deductible Yes Part B excess charges Yes Yes Yes = 100% Other strategies Part A coinsurance Yes Yes Yes Yes Yes Yes Yes Part B coinsurance Yes Yes Yes Yes 50%75% Yes Blood (3 pints) Yes Yes Yes Yes 50%75% Yes Part A hospice care Yes Yes Yes Yes 50%75% Yes Competent nursing center Yes Yes 50%75% Yes Part A deductible Yes Yes Yes 50%75%50%Part B deductible Yes Part B excess chargesForeign travel emergency80%80%80% Yes = 100% This can give you peace of mind since you won't be shocked by high medical costs.
Strategies F and C have better protection than Strategy G, however you can't get them if you're a brand-new enrollee. If you buy a strategy with low protection when you're 65 and later on decide to update to something better, such as Plan G, companies may estimate you a high rate or reject you coverage entirely.
Plan G has the finest coverage for many seniors and others on Medicare. After you pay this, Strategy G will spend for treatment such as doctor gos to, blood tests or outpatient medical treatment. Pros and cons of Plan G Popular plan that covers nearly all of your health costs Frequently a much better value than Plan F Rates can be costly, at $180 monthly, on average Cheaper strategies might be a better deal if you hardly ever go to the physician Strategy F has the very best protection of any Medigap strategy in general.
Insurance in Costa Mesa CABenefits and drawbacks of Strategy F Pays for nearly all medical expenses High monthly rates Not readily available to new Medicare enrollees Strategy N has comparable protection to Strategy G but costs less. With Strategy N, you need to pay $20 for physician sees and $50 for trips to the emergency clinic.
Securing Cheap Individual Health Insurance Quotes
Advantages and disadvantages of Plan N Yes Covers nearly all of the costs you're responsible for with Medicare Yes Strategy N costs about $137 each month, which is $43 monthly less than Plan G Extra costs you're accountable for paying when you go to the doctor might cancel out savings You might have extra costs if your doctor does not accept the rates set by Medicare High-deductible Plan G has the most inexpensive regular monthly rate of any Medigap policy.
Keep in mind, companies can charge greater rates or reject protection due to the fact that of your health history if you change Medicare Supplement plans outside the 6 months around your 65th birthday. That suggests you might be stuck to a high-deductible Strategy G when you're older and in even worse health, costing you more in the long run.
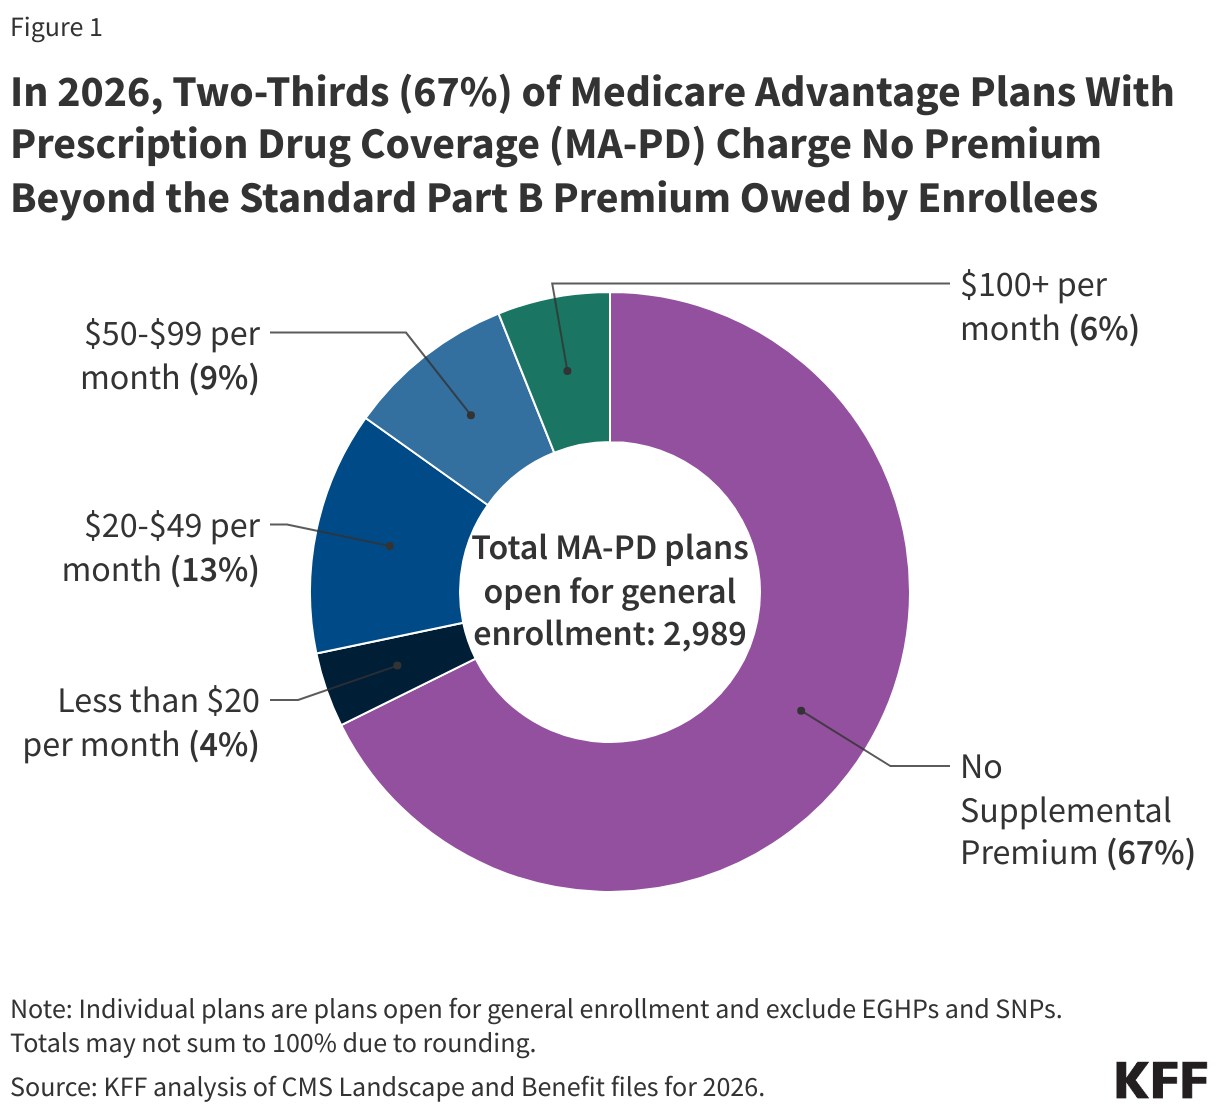
This suggests that Medicare Supplement Strategy G from AARP/UnitedHealthcare provides you the very same protection as Strategy G from Aetna, Blue Cross or any other business.

Latest Posts

Understanding 2026 Medicare Benefit Rules and Seniors

Optimizing Indexed Universal Life Policy Benefits for Retirement

Why Whole Life Insurance Works